Does your liability policy exclude assault and battery?
Many bar and restaurant liability policies exclude fights and altercations unless that coverage is added back. If you serve after dark, it's one of the first things we check.
Independent insurance agency
Every client, from a property portfolio to one family car, gets the same personal attention, in English or Spanish.
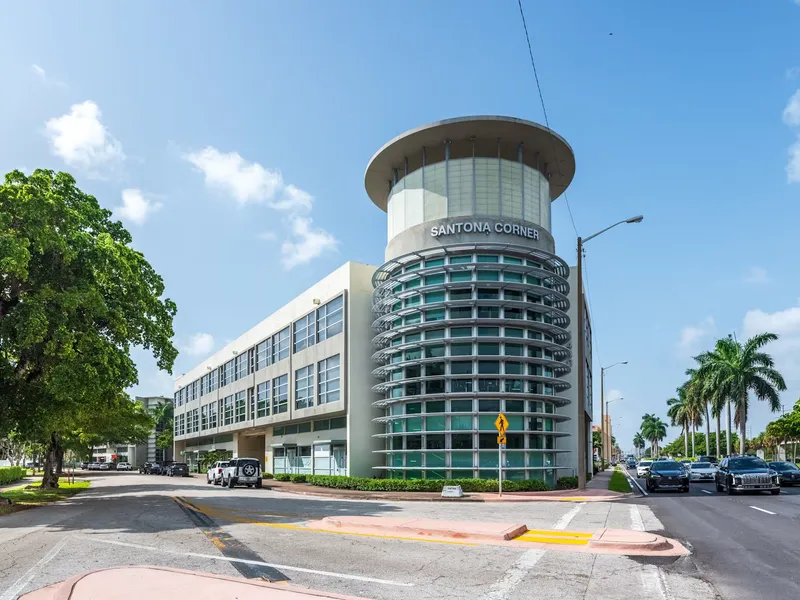
Coral Gables, Florida
Who we insure
Focusing on hospitality and real estate is how we learned where generic policies fall short, and what your business actually needs covered.
 Hospitality
Guests, alcohol, and food service create risks a generic policy isn't built for. We build coverage around how you actually operate, from the kitchen to the rooftop bar.
 Short-term rentals
Your rental is a hospitality business, and we insure it like one. Standard homeowners policies usually exclude rental use, so we cover properties built for frequent guest turnover.
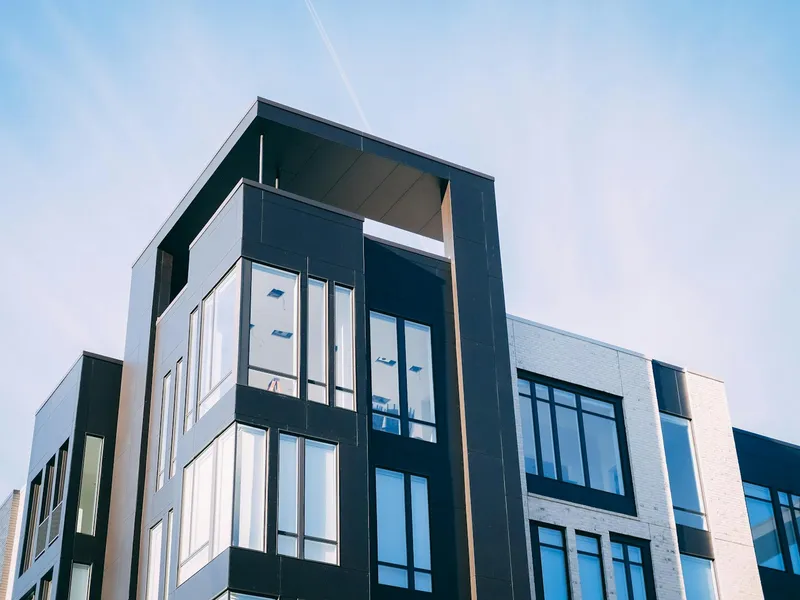 Real estate investors
One advisor, one program, every door. Instead of a separate policy, renewal date, and deductible for each property, we build one program that grows with your portfolio.
What a specialist catches
We see the same risks over and over, so we know where policies in your industry tend to fall short. Here are a few of the questions we ask on every review.
Many bar and restaurant liability policies exclude fights and altercations unless that coverage is added back. If you serve after dark, it's one of the first things we check.
Landlords and lenders often set minimum limits for any venue that pours drinks. We check your coverage against the contracts you've actually signed.
Hired and non-owned auto coverage protects the business when employees use personal vehicles for deliveries, catering, or supply runs.
A power failure can wipe out a walk-in cooler overnight. Spoilage coverage is often an add-on, not a given.
Innkeepers liability covers guests' property in your care, like luggage and items left with the front desk. A standard liability policy may not.
Pools, fitness rooms, shuttles, rooftop bars, and events all change your risk. We make sure each one is disclosed and covered, so a claim doesn't turn into a dispute.
Business income coverage can replace lost revenue and ongoing expenses after a covered loss. We check the limits and waiting period against your real numbers.
Hotel bars, room service, and private events all serve alcohol. Your liquor liability should reflect every place a drink gets poured.
Most standard homeowners policies exclude or limit coverage when the home is rented to guests. The time to find out is before a guest checks in, not after a claim.
Host protection programs come with their own limits and exclusions. They can be a backstop, but they aren't a policy built around your property.
If a covered loss makes your rental unlivable, loss-of-income coverage can replace the bookings you miss while it's repaired.
In a condo, the association's master policy and your unit policy split the building between them. We make sure nothing falls through the middle.
Separate policies mean separate renewal dates, deductibles, and gaps. We build one program that grows with your portfolio.
Many property policies limit coverage once a building has been vacant for 60 days. Renovations and long turnovers need a plan.
Loss of rents coverage replaces rental income while a covered loss is being repaired, so the mortgage still gets paid.
An umbrella policy can extend liability limits across every property at once, instead of raising limits one policy at a time.
Not sure how your policy answers these? Send us what you have. We'll walk through it with you, question by question.
Have us review my coverageFlorida storm season · June 1 to November 30
Know what you'd owe before a storm is on the map.
The deductible
The wait
The freeze
How it works
No call center and no handoffs. Here's what happens after you reach out.
A short conversation about your locations, guests, staff, and what you serve or rent. Bring your current policy and renewal date if you have them.
We read your current coverage against how you actually run, and against what your lease, lender, or condo association requires.
As an independent agency, we compare coverage and pricing across several carriers and explain the differences in plain language.
Certificates, new locations, added properties, mid-year questions, and a real look at every renewal. Same person, every time.
Who you'll work with
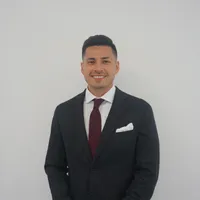
Jose Beaumont started Coastline after almost nine years in the insurance industry. He works directly with hospitality and real estate clients, from the first conversation through renewals, in English and Spanish.
When a lender needs a certificate by Friday, or a storm is on the way, you'll know exactly who to call: the same person who reviewed your policy.
Why Coastline
Here's how working with us compares with the two usual ways Florida owners buy coverage: a typical local agency, or an online insurer.
| What you get | Coastline | A typical agency | An online insurer |
|---|---|---|---|
| Who you work with | Jose, the founder, in English or Spanish, from first call to every renewal | A service team, and your contact can change | An app, a chat window, or a call center |
| Focus | Hospitality and real estate, every day | A little of everything: auto, home, life, business | One product, quoted one address at a time |
| Storm planning | Deductibles in dollars, flood waiting periods, and storm-season timing, up front | Often a line about hurricanes | Mostly left to help articles |
| Everything you own | Your venue, your rentals, and your home and auto with one advisor | Varies | Usually one policy type |
| Carriers compared | Several, side by side | Varies; captive agents sell one company | Their own policy |
A general comparison. Every agency is different, and some do parts of this well.
After you're covered
Insurance earns its keep when you need something from it. Here's what that looks like with us.
Landlord, lender, event venue, or vendor asking for proof of insurance? Request a certificate online and we'll get it sent over.
Request a certificateYour restaurant, your rentals, your family's home and cars. Instead of one agent for the business and another for the house, you get one person who knows the whole picture.
Home and auto for clientsWe look at your renewal before it arrives and shop it again when your business or the market has changed. No rubber stamps.
New location, another property, a new vehicle, more staff. Tell us what changed and we'll update your coverage to match.
If something happens, call us. We'll help you report the claim and understand what your policy covers.
Questions
Don't see yours? Call (786) 622-2873 or email jose@coastlineinsure.com.
We're not tied to one insurance company. We compare coverage and pricing across several carriers, so you get the option that fits, not just the one an agent happens to sell.
It's our focus and where our experience runs deepest: hotels, restaurants, bars, short-term rentals, and investment properties. We also place general commercial coverage for other Florida businesses, and home and auto for our commercial clients and their referrals.
Yes. We're based in Coral Gables and work with businesses and property owners across Florida.
Usually not. Standard homeowners policies often exclude or limit coverage for short-term rental use. We'll look at what you have and what your rental actually needs.
As early as you can. Share your renewal date and we'll reach out with enough time to compare options, instead of the week your policy expires.
Basic details about your business or property, plus your current policy and renewal date if you have them. If you're missing something, that's fine. We'll work through it together.
Sí. Jose trabaja con sus clientes en inglés y en español, desde la primera conversación hasta cada renovación. Vea el sitio completo en español.
No. The form doesn't bind, change, or cancel any coverage. We'll confirm everything with you before any policy is bound or changed.
Let's talk coverage
Tell us about your business or property and when your current policy renews. We'll reach out with enough time to compare real options, not the week it expires.
Free quotes, no obligation · Hablamos español · Monday to Friday, 9 AM to 6 PM